Accounts Receivable Management & MSME 45-Day Payment Mandate (Section 43B(h))
Risk Mitigation & Solvency
An authoritative legal and tax analysis of Section 43B(h) of the Income Tax Act, 1961 and the MSMED Act, 2006. How enterprises must structure payment terms, verify supplier Udyam registrations, and avoid severe tax disallowances.
"“Delaying payments to registered MSME suppliers is no longer just a trade negotiation; it triggers immediate 30%+ income tax penalties and mandatory compound interest.”"
Statutory Timelines Under Section 15 of MSMED Act
- 15-Day Default Mandate: Where no written agreement exists between buyer and supplier, payment must be completed within 15 days of invoice or delivery.
- 45-Day Maximum Cap: Even if a written commercial contract specifies 60 or 90 days credit, Section 15 strictly caps valid credit at 45 days.
- Applicability Scope: Applies exclusively to Micro and Small enterprises registered under Udyam. Does not apply to Medium enterprises or pure traders.
- Tax Disallowance Consequence: Outstanding sums as on 31st March not paid within the statutory period are added back to taxable income, creating huge advance tax liabilities.
- Compound Interest Penalty: Mandates compound interest with monthly rests at three times the RBI bank rate, which is non-deductible for income tax purposes.
Operational Best Practices for Corporate Buyers
Every enterprise must update its ERP and purchase workflows: obtain annual Udyam verification declarations from all active vendors, categorize accounts payable by MSME status, and automate payment batching to settle invoices within 40 days to maintain full tax deductions.
📋 Professional Practice Advisory Note
Lav K Sharma & Co., Chartered Accountants delivers specialized Virtual CFO advisory, corporate debt structuring, statutory audit management, and direct tax compliance across India. For confidential consultation with our partners, connect directly with our office.
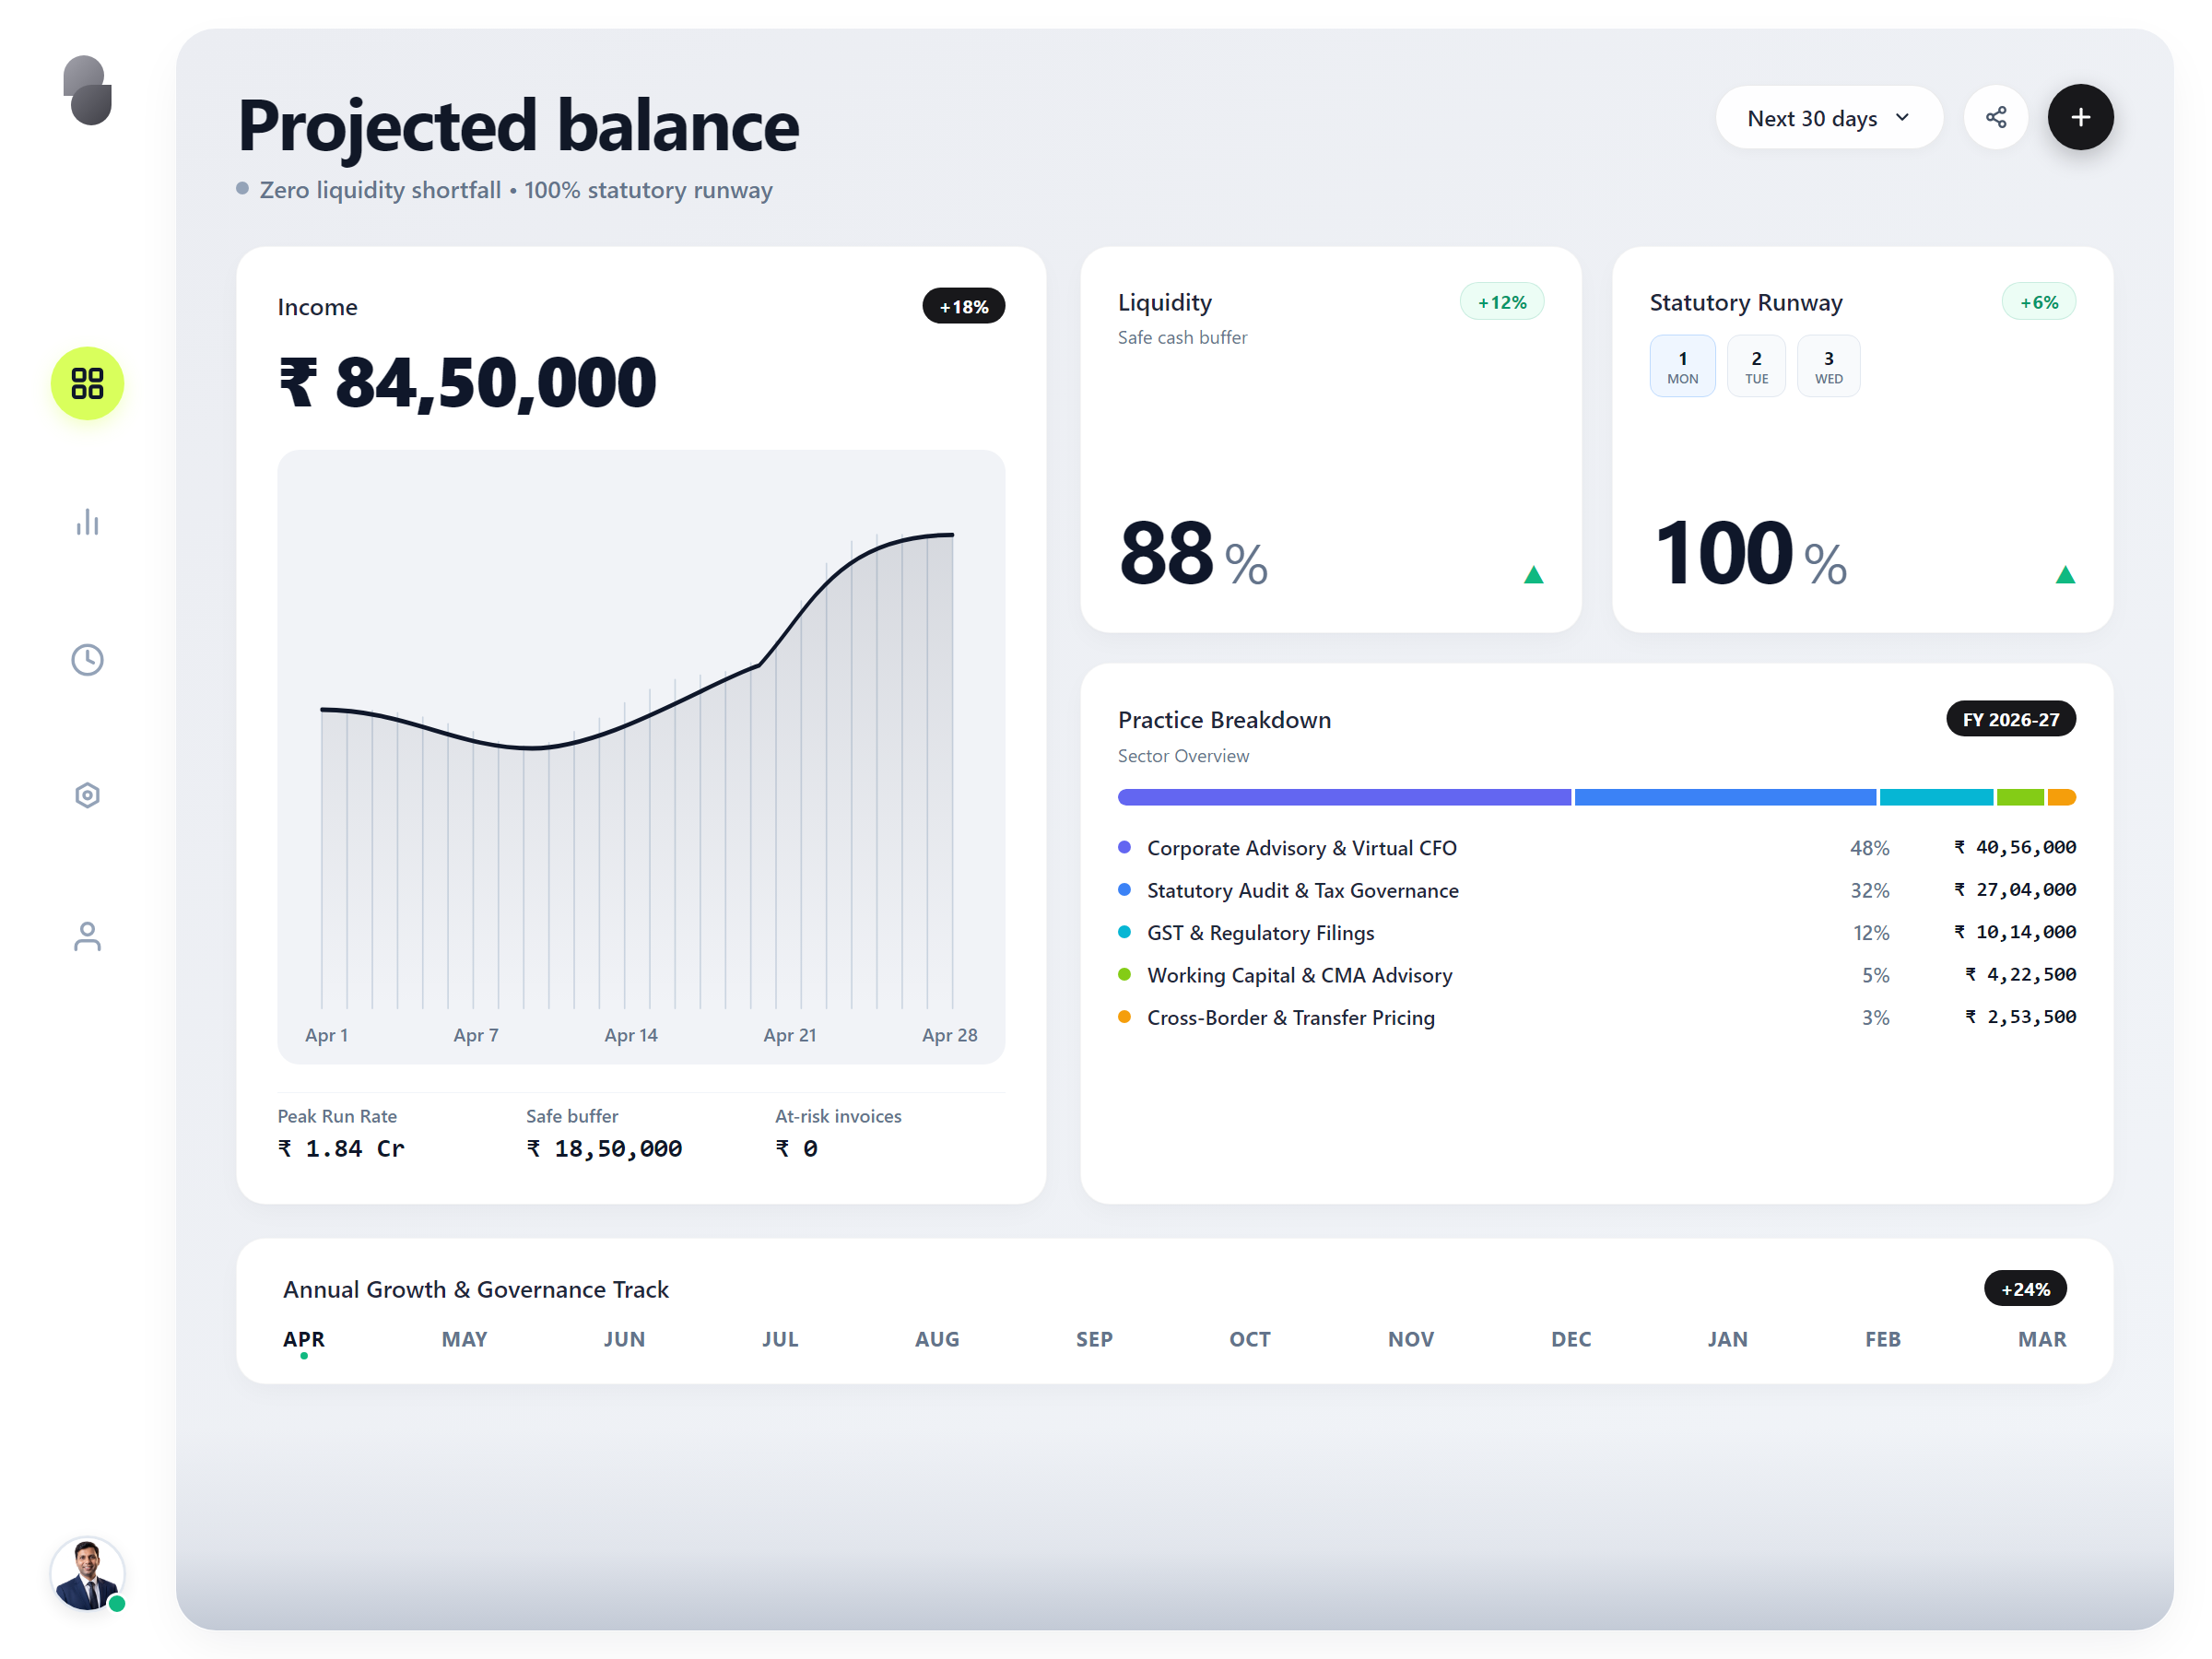
The 13-Week Rolling Cash Flow Forecast
Annual budgets are insufficient for managing working capital volatility. Well-run corporate finance desks rely on a rolling 13-week cash flow model updated every Monday morning:
- Weeks 1 to 4 (Deterministic): Known customer collection commitments, confirmed payroll obligations, statutory tax liabilities, and fixed vendor payouts.
- Weeks 5 to 8 (Operational): Anticipated project billing milestones, scheduled raw material purchases, and advance tax tranches.
- Weeks 9 to 13 (Strategic): Projected seasonal sales inflows and planned capex disbursements.
By rolling this 13-week projection forward each week, a liquidity shortfall is visible 8 to 10 weeks in advance—providing ample runway to adjust procurement, accelerate debtor recovery, or arrange promoter loans.
See also
Strategic Financial Leadership & Advisory
Lav K Sharma & Co. delivers Virtual CFO leadership, corporate tax planning, and statutory compliance discipline to growing enterprises across India.