What Lenders and Private Equity Investors Review: Margins, Cash Flow, and DSCR
Risk Mitigation & Solvency
An inside look into institutional credit underwriting and investor due diligence. How banks evaluate Debt Service Coverage Ratio (DSCR), Interest Coverage, Tangible Net Worth, and audited financial credibility.
"“Investors buy future growth, but commercial lenders lend against proven debt servicing capability.”"
Core Credit Underwriting Metrics Evaluated by Banks
- Debt Service Coverage Ratio (DSCR): Measures free operating cash available to service principal and interest. Banks typically demand a minimum DSCR of 1.50x to 1.75x.
- Interest Coverage Ratio (ICR): EBIT divided by total finance costs. An ICR above 3.0x indicates solid operating resilience against interest rate cycles.
- Tangible Net Worth (TNW): Paid-up share capital plus free reserves minus intangible assets and deferred tax assets. Represents the promoter’s true skin in the game.
- Total Outside Liabilities to Adjusted Net Worth (TOL/ANW): Evaluates overall enterprise leverage, including trade payables and statutory obligations.
Eliminating Red Flags in Credit Appraisals
Banks immediately penalize balance sheets containing circular related-party advances, long-outstanding unbilled receivables, and high inventory holding periods. Ensuring your financial statements undergo rigorous pre-submission review guarantees swift loan sanctions and competitive interest spreads.
📋 Professional Practice Advisory Note
Lav K Sharma & Co., Chartered Accountants delivers specialized Virtual CFO advisory, corporate debt structuring, statutory audit management, and direct tax compliance across India. For confidential consultation with our partners, connect directly with our office.
The 13-Week Rolling Cash Flow Forecast
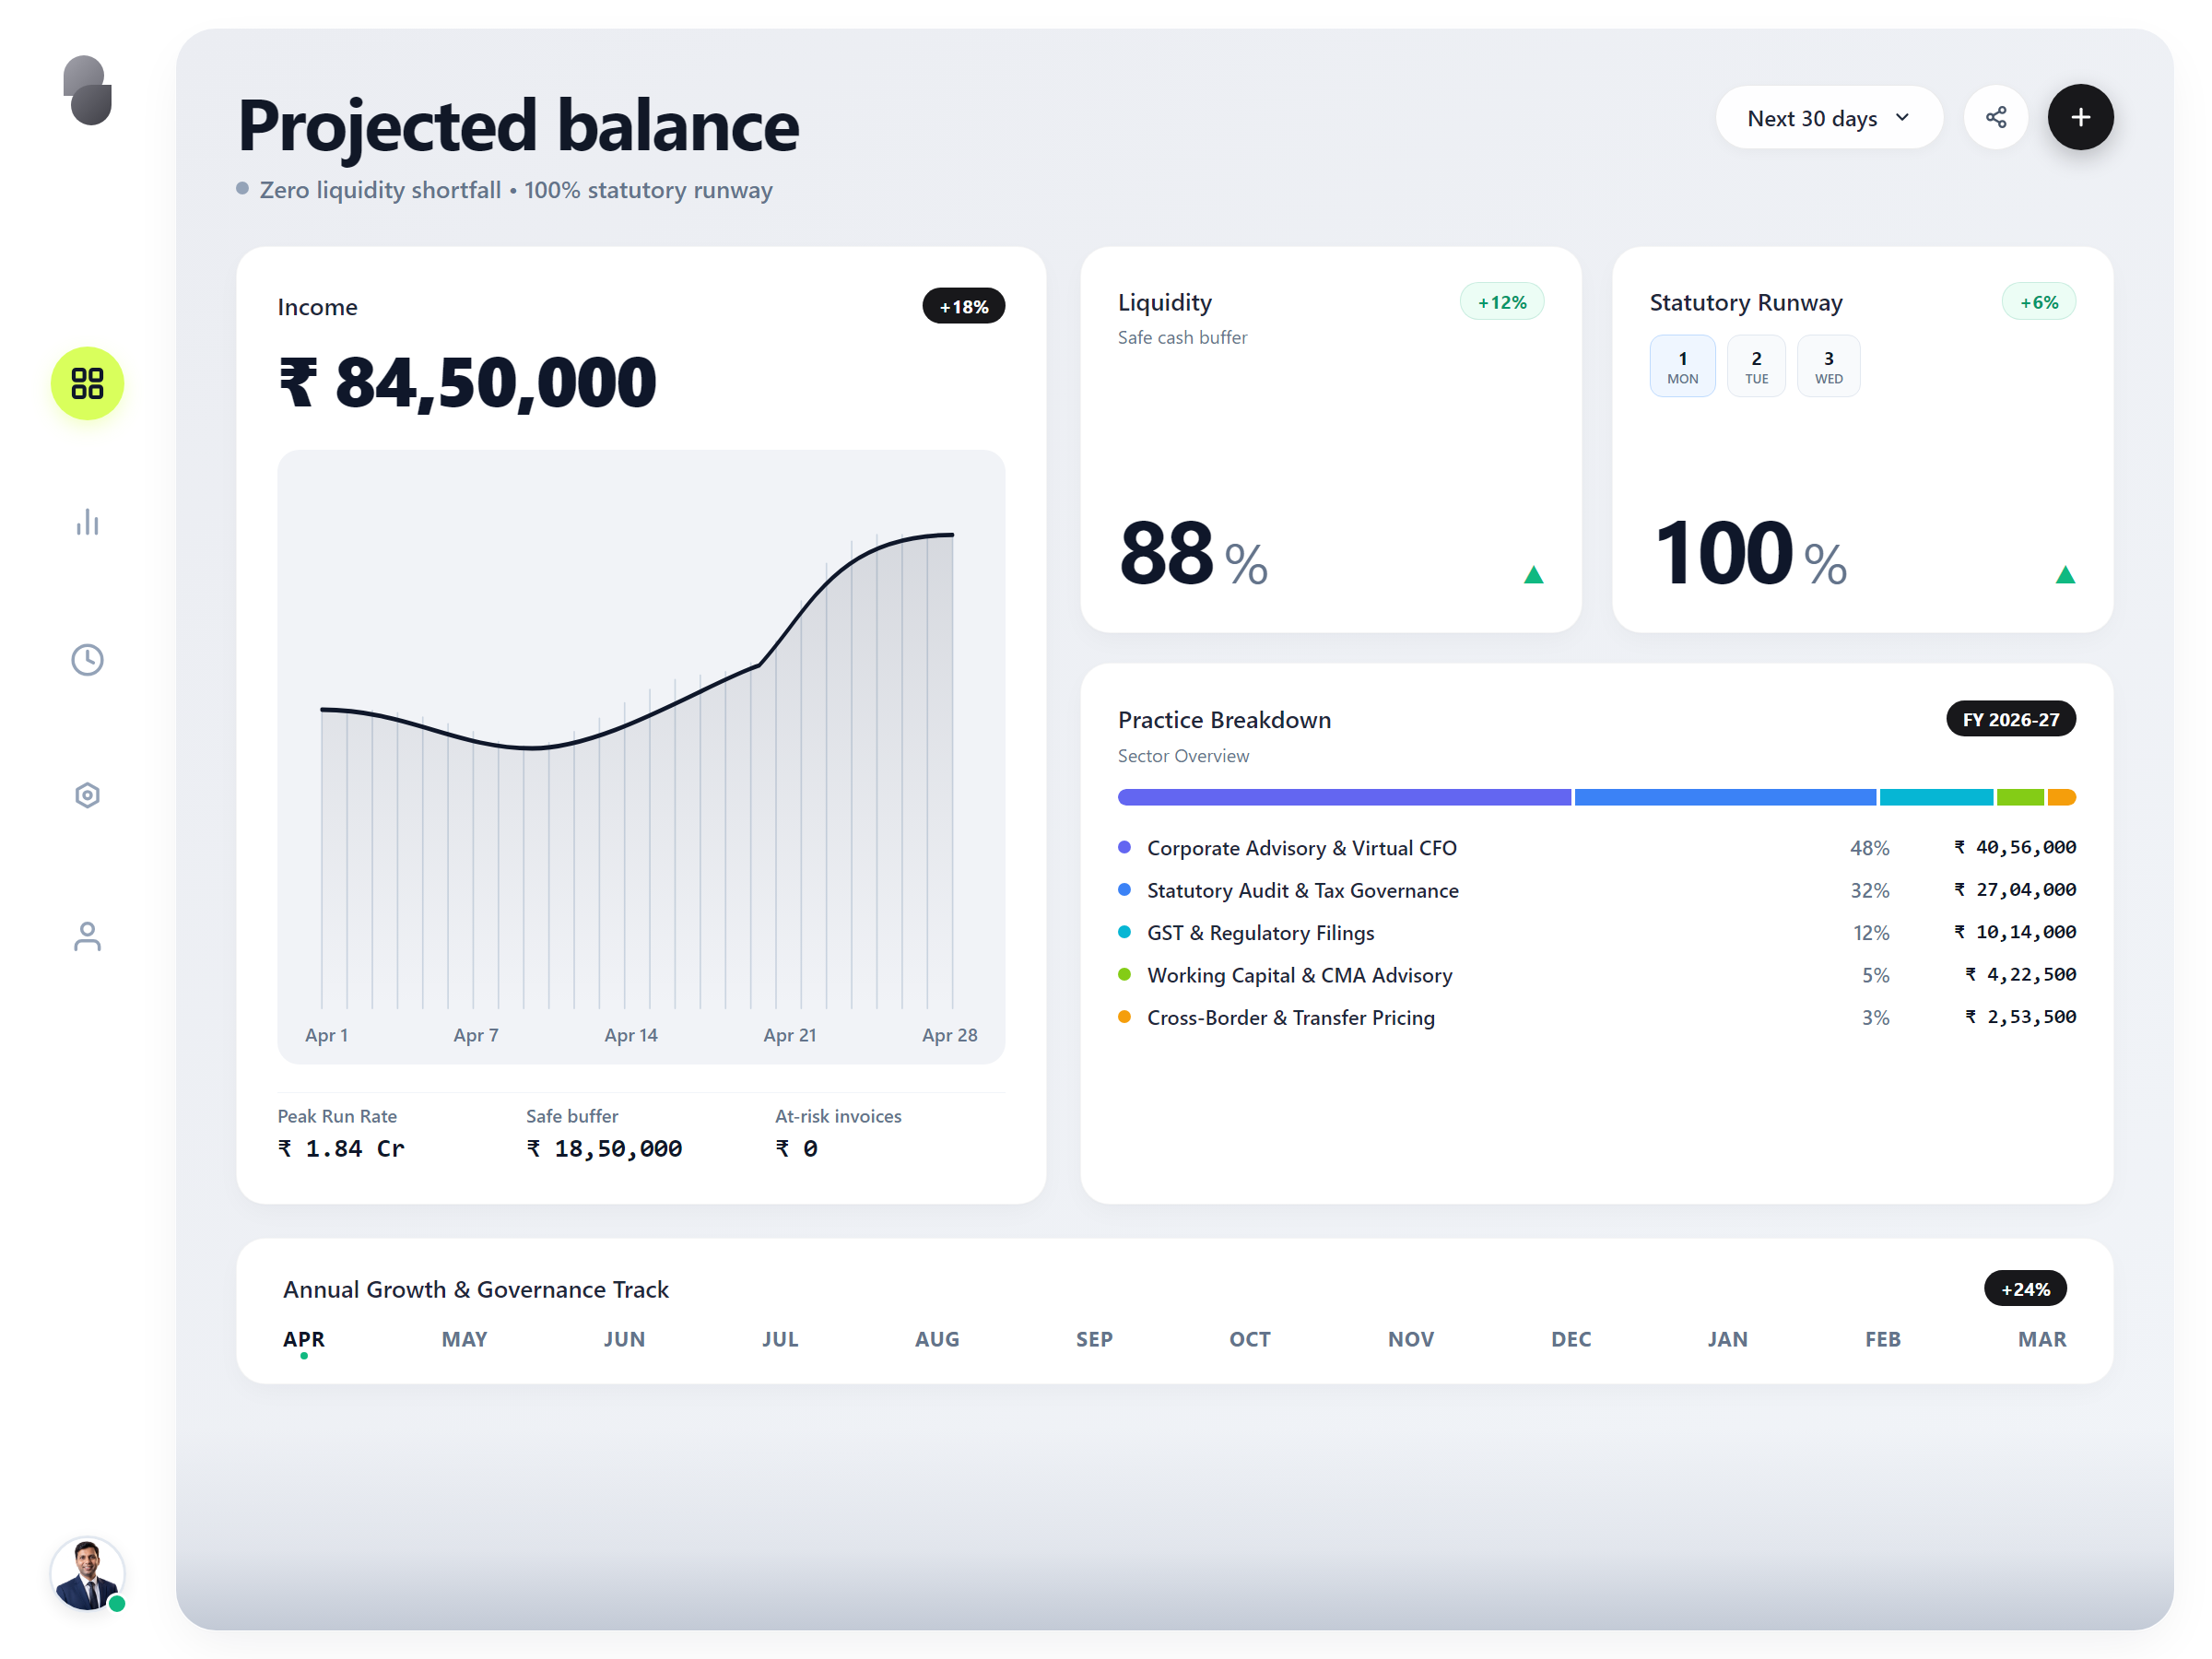
Annual budgets are insufficient for managing working capital volatility. Well-run corporate finance desks rely on a rolling 13-week cash flow model updated every Monday morning:
- Weeks 1 to 4 (Deterministic): Known customer collection commitments, confirmed payroll obligations, statutory tax liabilities, and fixed vendor payouts.
- Weeks 5 to 8 (Operational): Anticipated project billing milestones, scheduled raw material purchases, and advance tax tranches.
- Weeks 9 to 13 (Strategic): Projected seasonal sales inflows and planned capex disbursements.
By rolling this 13-week projection forward each week, a liquidity shortfall is visible 8 to 10 weeks in advance—providing ample runway to adjust procurement, accelerate debtor recovery, or arrange promoter loans.
See also
Strategic Financial Leadership & Advisory
Lav K Sharma & Co. delivers Virtual CFO leadership, corporate tax planning, and statutory compliance discipline to growing enterprises across India.